Commercial underwriting software: what it automates and what underwriters keep
For commercial and CRE lenders: what underwriting automation takes off an analyst's desk, the benefits it brings, and how multifamily deals are underwritten.

Key takeaways
- Commercial underwriting software automates the data work in a commercial loan, so underwriters start from a filled spread and a list of exceptions. The credit decision stays with people.
- Done by hand, spreading means analysts retype statements and map each borrower's line names onto the lender's template before any analysis starts.
- The OCC names debt yield, DSCR, LTV, loan-to-cost and minimum net worth or liquidity as the most common financial covenants on income-producing CRE loans. Each is calculated from figures in the loan file.
- Multifamily underwriting weighs the three C's: the sponsor's credit, the property's capacity to pay (DSCR) and the collateral (LTV).
- Test any tool on your messiest files: scanned statements, property managers' own T-12 layouts and rent rolls with hundreds of units.
On this page
Commercial underwriting software automates the document work in a commercial loan: it reads the borrower's financial statements, tax returns and bank statements, plus the T-12 and rent roll on a property loan, spreads the figures and checks them against credit policy. Underwriters keep the credit decision. The payoff is faster spreading, the same policy applied to every deal, a record of where each number came from and more deals per underwriter.
What document automation does in commercial underwriting#
A commercial loan file arrives as PDFs, scans and spreadsheets, each in the borrower's own format. Automation turns it into a spread and a short list of exceptions.
- Financial statements
- Tax returns
- T-12s and rent rolls
- Bank statements
- 01Extract every line
- 02Spread into the template
- 03Check ratios and covenants
- 04Flag exceptions
In a manual process, the first two stages take the most time: retyping statements and mapping each borrower's line names onto the lender's template. The spread feeds the ratios credit policy tests: debt service coverage (DSCR), debt yield and, with the appraised value, loan-to-value (LTV). The OCC lists these, with loan-to-cost and minimum net worth or liquidity, as the most common financial covenants on income-producing CRE loans. Financial statement spreading shows the mapping line by line.
Benefits of automating commercial underwriting#
Faster spreading
Statements and returns arrive as data, so analysts check a filled spread instead of keying one.The same policy on every deal
Every file gets the same ratio and covenant checks, whoever underwrites it.An audit trail
Each number links back to the page and line it came from, for credit committees and examiners.More deals per underwriter
Time moves from data entry to judgment, so the same team can review more deals.Fewer late conditions
Missing years, statements that don't tie out and stale documents surface at intake, not days before closing.
Manual vs automated commercial underwriting#
Retyping the file
- Analysts retype statements and returns into the spread, line by line
- Each analyst maps a borrower's line names a little differently
- Figures that disagree across documents surface late, if at all
- A multi-year, multi-entity file takes hours before analysis starts
Reviewing a filled spread
- Statements and returns arrive extracted, each value linked to its source line
- The same mapping and checks run on every file
- Values the model is unsure about go to an analyst first
- Analysts start from a filled spread and a list of exceptions
Multifamily underwriting: the three C's#
Multifamily loans are a common case for automation: each property runs like a small business, with many units, several income streams and its own expenses. Underwriters weigh three things.
Credit
The sponsor's credit history, track record with similar properties and financial strength, from personal and entity financial statements, tax returns, a schedule of real estate owned and bank statements.Capacity
Whether the property's income covers the loan. DSCR is net operating income (NOI), from the T-12 and rent roll, divided by annual debt service; above 1.0, the property earns more than the payments.Collateral
Whether the property holds its value. LTV is the loan amount divided by the property's value, from the appraisal and purchase contract; a lower LTV leaves more cushion.
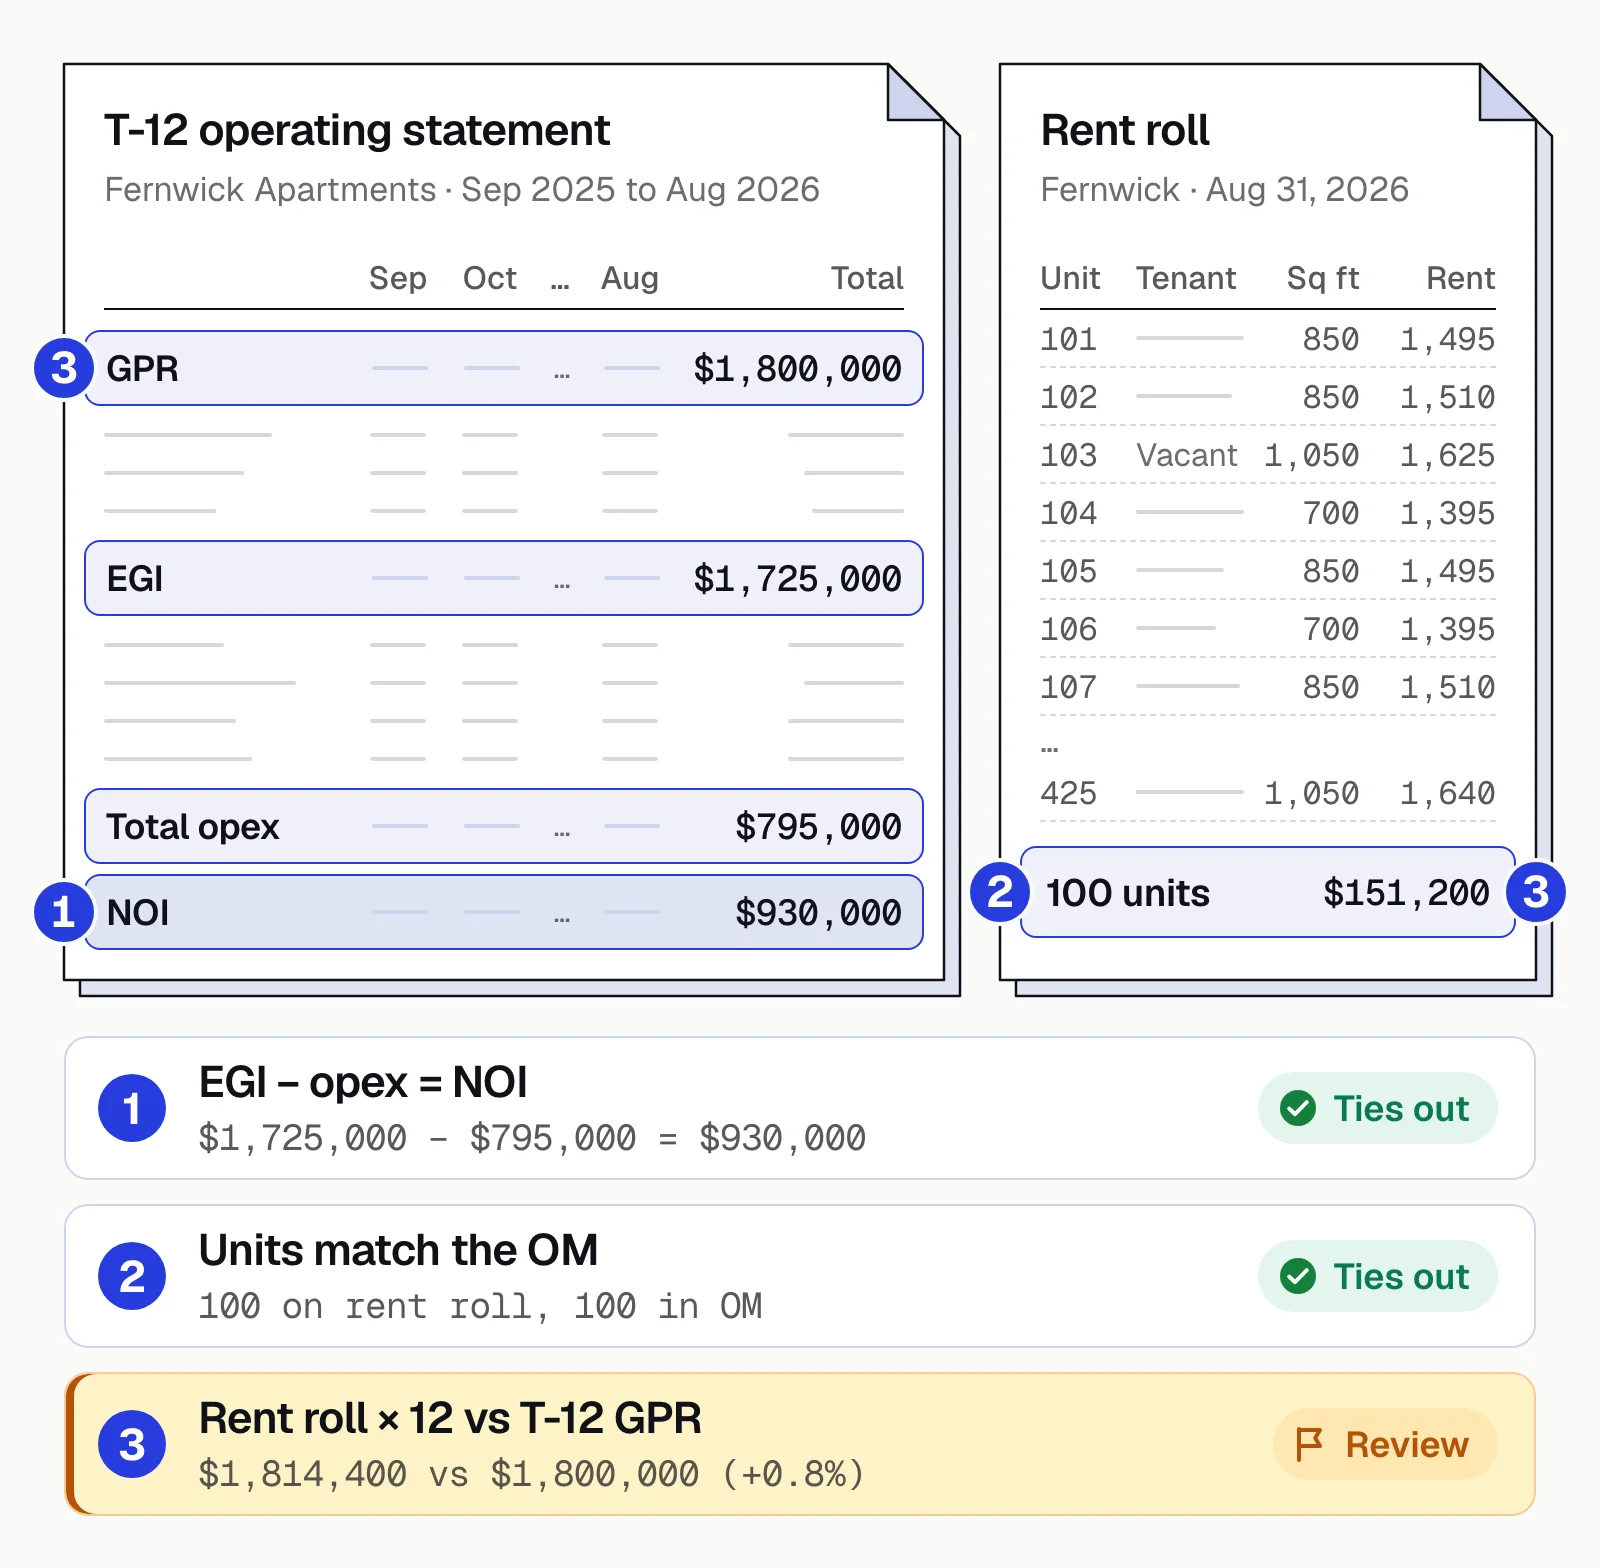
With the figure's $930,000 of NOI, a loan with $700,000 of annual debt service has a DSCR of 1.33 ($930,000 ÷ $700,000). Capacity is where the manual time goes, because every T-12 and rent roll comes in its own layout, with different line names and unit mixes. See T-12s in real estate and rent roll automation.
How to automate commercial underwriting#
Lenders combine tools by job. A loan origination or credit platform holds the spread and the decision (nCino's Automated Spreading, for example, reads tax returns and company-prepared statements), CRE lending platforms such as Blooma parse loan-package documents into credit analysis alongside your LOS, and document extraction feeds whichever of them you run. The best CRE underwriting software compares ten CRE tools, Blooma among them.
Docsumo is an intelligent document processing (IDP) platform. For financial spreading and CRE underwriting, it reads financial statements, tax returns, bank statements, T-12s and rent rolls, scans included, joins tables that run across pages and sends values it's unsure about to an analyst, with the source line highlighted. Cross-document validation, such as checking statements against returns, is on the Enterprise plan, along with case management. Data downloads to Excel or goes through API and webhooks into your spread or loan system. It doesn't underwrite the deal: your spread or credit system calculates DSCR and covenants, or you add that as a step you set up in the Docsumo workflow.
- 99%field-level accuracy across 250+ document types
- 95%+of documents processed straight through, without manual review
- <5 minper document, down from 2+ hours
The bottom line#
Automating commercial underwriting doesn't automate the credit decision. It takes the retyping out of spreading, applies the same checks to every deal and shows where each number came from, so underwriters spend their time on the borrower and the property. Start with the documents your analysts spend longest on, and test any tool on your messiest files.
Book a demo with a few of your own borrower files, or start a free trial.
Frequently asked questions#
What is commercial underwriting?
Commercial underwriting is how a lender decides whether to lend to a business or against an income-producing property, and on what terms. The underwriter analyzes the borrower's financial statements and tax returns, the property's income and value, and any guarantors, then sizes the loan to the lender's credit policy.
What is commercial underwriting software?
Software that automates the data work in commercial underwriting, so the underwriter starts from a filled spread and a list of exceptions. Its core features are reading borrower and property documents, spreading the figures into a standard template, calculating ratios such as DSCR, debt yield and LTV and testing them against policy, routing exceptions to an analyst with the source shown, and passing the results to the credit memo or loan system.
Is AI replacing underwriters?
No. AI reads the documents, fills the spread and flags exceptions, which takes the data entry off the underwriter's desk. Judgment on the borrower, the market and the structure of the deal stays with the underwriter and the credit committee. See how automated underwriting software works for where decision engines fit.
What tools automate commercial loan underwriting for US lenders?
Lenders combine tools by job: a loan origination or credit platform such as nCino, whose Automated Spreading reads tax returns and company-prepared statements; CRE lending platforms such as Blooma, which parse loan-package documents into credit analysis; and document extraction such as Docsumo, which feeds whichever spread or loan system you run. See the best CRE underwriting software.
How does AI-powered multifamily underwriting software reduce data entry errors?
It reads each T-12 and rent roll line instead of someone retyping it, ties the documents out against each other, such as rent roll rent against the T-12's gross potential rent, and sends values it's unsure about to a person with the source line shown.
Can due diligence for CRE loans be automated?
The document side can. Software reads the T-12, rent roll, leases, bank statements and financial statements, ties the figures out against each other and flags what disagrees, so analysts start from a checked file. Third-party reports such as the appraisal and the environmental and property condition reports still need an expert's review.